Leverage, Not Liability: How Asia's Specialist Service Networks Are Fueling US Company Expansion
The instinct to eliminate intermediaries has become something of a corporate religion in American business culture. Rooted in the logic of Silicon Valley disruption and lean operations, the belief that cutting out the middleman always reduces cost and accelerates growth has taken on an almost axiomatic quality in US boardrooms. But in Asia—where regulatory environments shift without warning, business relationships are cultivated over years rather than quarters, and a single misstep in customs documentation can halt a shipment for weeks—that doctrine is quietly costing US companies time, money, and market position.
A closer examination of how Hong Kong-based consultants, freight forwarders, and regional trade specialists actually operate reveals something counterintuitive: these service layers are not friction in the system. In many cases, they are the system. And for US companies serious about capturing Asia-Pacific growth, understanding that distinction may be the single most consequential strategic shift they make.
The Disintermediation Myth, Applied to the Wrong Geography
Disintermediation works when markets are transparent, regulations are stable, and the primary barrier to efficiency is price markup. In those conditions, removing a middleman genuinely does create value. But Asia-Pacific trade environments—particularly those involving Southeast Asian manufacturing corridors, cross-border logistics through Hong Kong, and regulatory compliance across multiple jurisdictions—share almost none of those characteristics.
Consider what a US company faces when it attempts to self-manage sourcing operations across Vietnam, Thailand, and Indonesia without regional expertise. Each country carries its own import duty schedules, certificate-of-origin requirements, and product compliance frameworks. Labor regulations evolve in response to domestic political pressures. Port congestion, seasonal disruption, and informal relationship dynamics all affect lead times in ways that no procurement software dashboard can fully capture. The company that attempts to navigate this environment from a headquarters in Austin or Atlanta is not cutting out a middleman—it is cutting out institutional knowledge it does not yet possess and cannot quickly replicate.
What Regional Expertise Actually Delivers
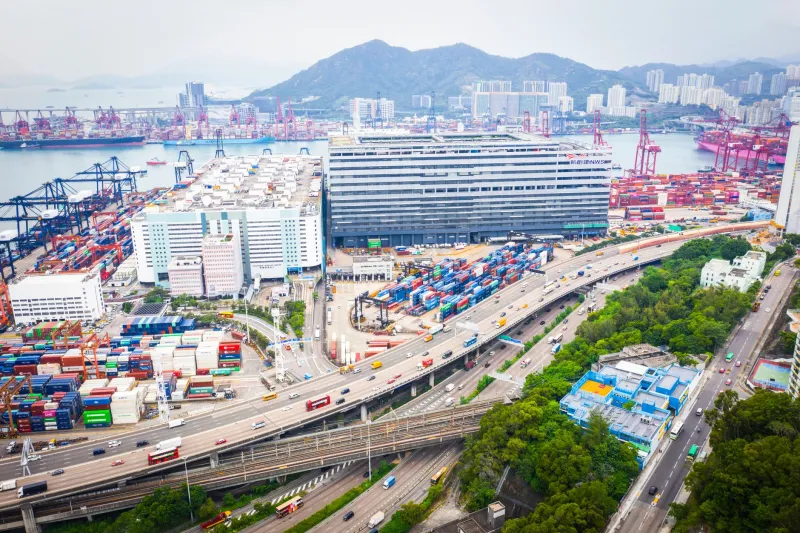
Hong Kong has long served as Asia's commercial nerve center, and its professional services ecosystem reflects that history. The consultants, logistics specialists, and trade advisors operating from this hub bring something that no internal hire can immediately replicate: embedded, real-time intelligence across multiple markets simultaneously.
When a US electronics importer engaged a Hong Kong-based trade consultancy to manage its Southeast Asia sourcing transition, the results illustrated this point clearly. The company had previously attempted to build an internal procurement team based in Singapore, only to find that vendor relationships in Malaysia and component certification processes in Thailand required a depth of local engagement that a small internal team simply could not sustain. After transitioning to a regional specialist firm, the company reduced its average vendor onboarding time by roughly 40 percent and avoided two separate regulatory compliance issues that would have triggered shipment delays during peak season—issues that the specialist firm identified through its existing government and industry contacts before they became problems.
This is not an isolated outcome. Across industries from consumer goods to industrial equipment, US companies that engage established regional intermediaries consistently report faster market entry, lower compliance-related losses, and more stable supplier relationships than those pursuing full vertical integration from the outset.
Regulatory Navigation as Competitive Moat
One of the most underappreciated advantages that regional service providers offer is regulatory foresight. Trade policy in Asia moves quickly, and the gap between a regulatory announcement and its practical implementation is often narrow. For a US company managing Asia operations from a distance, that gap can be nearly impossible to act on. For a Hong Kong-based consultant with active relationships across government agencies, industry associations, and customs authorities, it represents an actionable intelligence window.
In 2023 and into 2024, shifts in rules-of-origin interpretations across several ASEAN member states created significant exposure for US importers relying on preferential tariff treatment. Companies with regional advisory relationships were able to restructure their supply documentation and, in some cases, adjust sourcing geography ahead of enforcement changes. Companies without that regional layer absorbed the full compliance cost—fines, reclassification, and in some cases, the expense of emergency logistics rerouting.
The competitive moat created by this kind of regulatory intelligence is real and measurable. It does not appear on a cost-per-unit analysis, but it shows up in margin preservation, shipment reliability, and the ability to make sourcing commitments with confidence rather than uncertainty.
Speed Through Depth, Not Simplification
One of the most persistent misconceptions about regional service providers is that they slow things down—that adding a layer of coordination introduces delays, miscommunication, and decision-making friction. The evidence from companies operating in Asia at scale tells a different story.
Speed in Asian trade is not primarily a function of organizational simplicity. It is a function of relationship depth and contextual knowledge. A freight forwarder in Hong Kong with a twenty-year relationship with a specific port authority can resolve a customs query in hours that would take a self-managing US company days to even properly formulate. A trade consultant with direct access to a regional chamber of commerce can surface a market access opportunity—or flag a risk—before it appears in any publicly available report.
For US companies competing in categories where speed to market and supply chain agility translate directly into revenue, this kind of embedded expertise is not a convenience. It is a structural advantage.
Rethinking the Integration Calculus
None of this suggests that US companies should abdicate strategic control over their Asia-Pacific operations. The most effective model is not one of wholesale outsourcing but of deliberate integration—where internal teams set direction, manage key relationships, and make strategic decisions, while regional specialists execute with the local depth that internal teams cannot match.
This hybrid approach requires a shift in how US executives frame the value of regional service providers. Rather than evaluating them purely on fee-versus-savings metrics, the more accurate measure is opportunity cost: what market access, compliance protection, and operational speed are you forgoing by attempting to replicate internally what a specialist has spent decades building?
Hong Kong's professional services ecosystem exists precisely because Asia's commercial complexity creates genuine, durable demand for expertise that cannot be easily commoditized or automated. The US companies that recognize this—and build regional partnerships accordingly—are not accepting a compromise. They are acquiring leverage that their more insular competitors simply do not have access to.
In a trade environment defined by accelerating regulatory change, shifting manufacturing geographies, and intensifying competition for reliable supplier relationships, that leverage may be the most valuable asset a US company can hold.